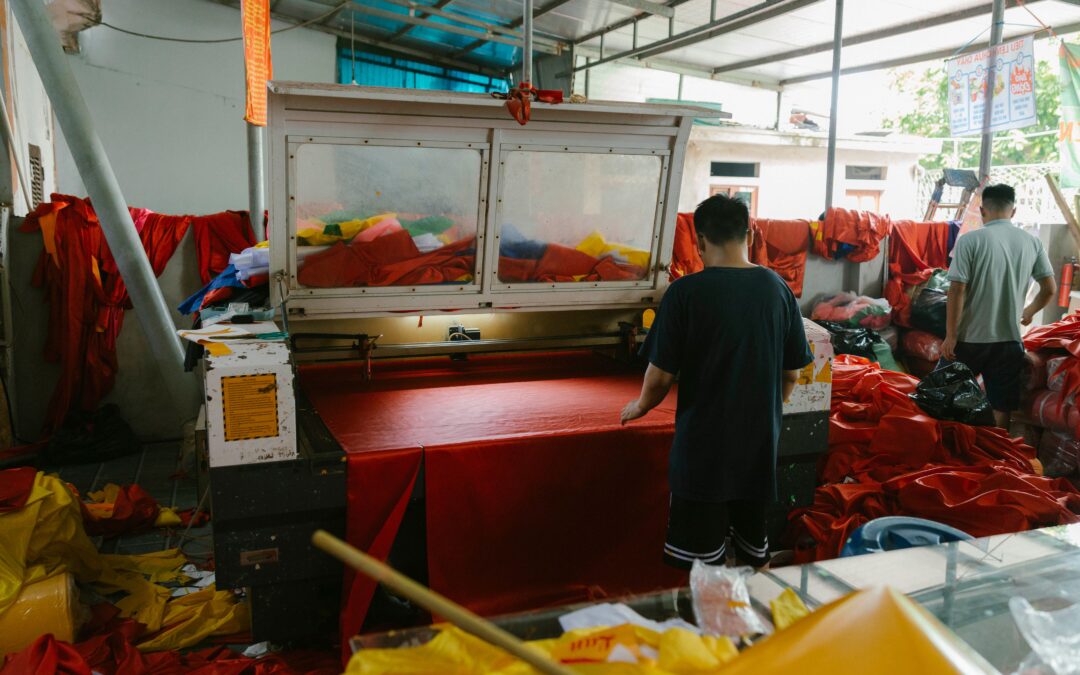
No lab coats. No patents. Just aluminum shavings, fabric samples, and a shop floor doing serious research and development without anyone calling it that. That’s the story behind a recent engagement with a custom canopy and architectural shade manufacturer, and it shows exactly how much money gets left on the table when R&D is assumed to mean something it doesn’t.
The company designs, manufactures, and installs custom canopy and architectural shade systems for commercial and residential customers nationwide, working in aluminum and steel to build walkway covers, entrance canopies, and fabric shade structures for a wide range of climates and building codes. Annual revenue sits around ten million dollars, with about fifty employees and a technical team of ten. On paper, a typical regional manufacturer. Under the tax code, a company is doing far more qualifying research than it realized.
Where the R&D Was Hiding
No two projects are alike. Each one comes with its own building facade, wind load, code requirements, and customer vision, none of which can be solved by pulling a standard part off a shelf. Solving them means evaluating alternative materials, stress-testing engineering designs, refining fabrication methods, and reworking installation techniques until they hold up on-site, every time.
That’s not incidental problem-solving. Repeated across dozens of projects a year, it’s the textbook definition of qualifying research activity. The federal R&D tax credit exists for exactly this: systematic, iterative work that resolves real technical uncertainty and improves a product’s function, reliability, or manufacturability, whether the end result is a semiconductor or a canopy. This team wasn’t publishing papers. But they were doing the work the credit was built to reward. It just needed to be found, documented, and quantified. For a deeper look at how the credit works, see our guide to the R&D tax credit.
The Results
Once the qualifying activities were identified and substantiated, the numbers did the talking. Across three tax years, the company generated $158,688 in gross federal R&D tax credits and $125,364 net.
Broken down by year: $51,438 net in 2023, $40,189 net in 2024, $33,737 net in 2025. That’s over $125,000 that would otherwise have gone straight to federal tax liability, redirected back into the business instead.
Why This Matters for Manufacturers
Manufacturers don’t miss this credit because they lack qualifying work. They miss it because they picture R&D as white coats and formal labs, patents pending. In reality, the credit belongs to any company doing iterative design, engineering, prototyping, and process improvement that resolves genuine technical uncertainty, no matter the industry or the headcount.
Custom manufacturers are especially well positioned, precisely because nothing they build is off the shelf. Every project that demands engineering judgment to solve a new structural, architectural, or performance problem is a potential source of qualifying expenses. The real question is rarely whether the work qualifies. It’s whether the company can identify, track, and document it well enough to hold up to scrutiny.
What This Looks Like in Practice
For this company, the credit study meant tracing how projects actually moved through the business: initial design, materials evaluation, prototyping, testing, final installation. Time and expenses tied to that process were identified and allocated across the relevant tax years, then calculated and substantiated to federal standards.
This isn’t a one-time windfall. The qualifying activity is baked into how the company operates, project after project, so the credit is there to claim again next year, and the year after, as long as the documentation keeps pace. For a manufacturer that’s always chasing better materials, better engineering, better fabrication, the R&D tax credit becomes a recurring source of capital, not a single event.
Doing this kind of design, engineering, or process-improvement work, even informally? There’s a good chance you’re sitting on a credit you haven’t claimed. The only way to know is to have it reviewed by someone who understands both the manufacturing floor and the tax code.
Think your business is leaving R&D credits on the table?
Book a call and find out what your engineering, design, and production work could be worth.
This material is provided for general informational purposes only and does not constitute tax, legal, or accounting advice. Every business’s facts and circumstances are different, and eligibility for the R&D tax credit depends on a detailed review of specific activities and expenses. Please consult with a qualified tax professional before making decisions based on this information.